Zip

- 56.94K Reviews
- 4.7
- Downloads
- 5,000,000+
Our take on Zip from Appgk
When I look at Zip as a shopping app, I see one central idea rather than a crowded marketplace: it gives me a way to split a purchase into flexible payments while shopping with participating merchants. That sounds simple, but the practical effect is important. Instead of treating checkout as the end of the shopping process, Zip makes the payment choice part of the decision about whether a purchase fits my budget.
I reviewed it from that angle because the payment option is where this app either becomes genuinely useful or turns into unnecessary friction. Zip is a free shopping app from Zip, Co., rated for Everyone, and it has built a large audience on both Android and iOS. Its average rating is 4.7 from around 107 thousand ratings, with more than 5 million installs. Those figures suggest that the basic idea is easy for many shoppers to understand, but popularity alone does not make flexible payments right for every situation.
Flexible payments are the feature that defines Zip
The most useful way to think about Zip is as a payment tool attached to shopping, not as a replacement for every store app or a general-purpose budgeting service. The app is designed to let me shop with flexible payment terms and use its payment option wherever Visa is accepted, subject to the terms shown during use. That broad reach is its main attraction: I do not have to limit myself to one narrow catalog to find value in it.
In ordinary shopping, I usually compare the item, delivery, return conditions, and final total before deciding. Zip adds another question: how will the cost be handled after checkout? That can make a planned purchase easier to manage, especially when the item is useful now but paying the entire amount at once would disrupt the rest of my monthly spending.
Best Parts of Zip
Things to Keep in Mind About Zip
There is a meaningful difference between flexibility and affordability. Zip can change the timing of payments, but it does not make an expensive product cheaper. I find that distinction essential. The app is most helpful when I already know the purchase is necessary, the total is clear, and I have a realistic plan for the later payments. It is much less helpful when flexible checkout becomes an excuse to buy something I would otherwise postpone.
The app’s store summary emphasizes shopping with flexible payment terms and using Zip anywhere Visa is accepted. In practice, that makes it more versatile than a payment plan tied to one retailer. I can consider it for a range of everyday purchases instead of downloading a separate financing app for each store. Still, acceptance at a broad group of merchants does not mean every transaction will feel identical, so I pay attention to the checkout details rather than assuming the same experience everywhere.
News and Features Related to Zip

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
What this changes at checkout
The strongest benefit is control over cash flow. If a purchase lands at an inconvenient point in the month, spreading the obligation can help me keep room for essentials. This is particularly relevant for planned household items, replacement electronics, clothing needed for work, or a larger basket that I have already compared carefully.
The less obvious benefit is decision clarity. When I see the payment arrangement before completing the order, I can judge the purchase against my upcoming commitments instead of looking only at the headline price. I recommend treating the displayed schedule as part of the price in your mind. The product still costs the full amount, and the payment dates matter just as much as the checkout total.
Don't want to read the full review?
That habit also exposes the app’s main limitation. Flexible payment products can feel smoother than traditional credit because the purchase is broken into smaller pieces. Smaller individual payments may be easier to overlook, though, especially if several purchases are active at the same time. Zip works best for someone willing to track commitments deliberately rather than relying on memory.
How I approach a purchase with Zip
I start outside the app by deciding whether I need the item and checking the merchant’s full cost, including delivery or other charges shown at checkout. Then I consider whether the proposed payment timing fits my actual income schedule. I do not judge the plan by asking whether the first payment looks comfortable; I ask whether every later payment remains comfortable alongside rent, utilities, food, and existing obligations.
Screenshots
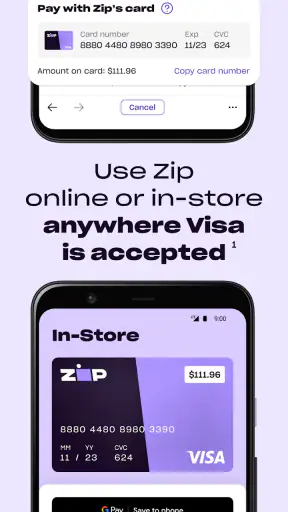
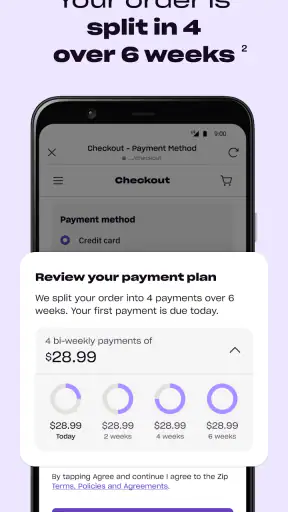
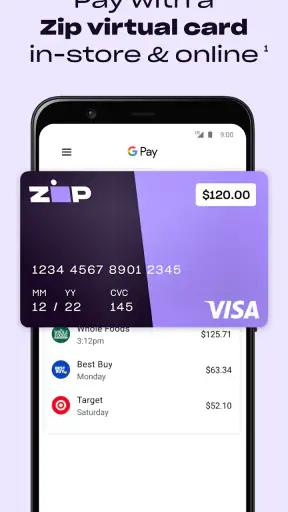
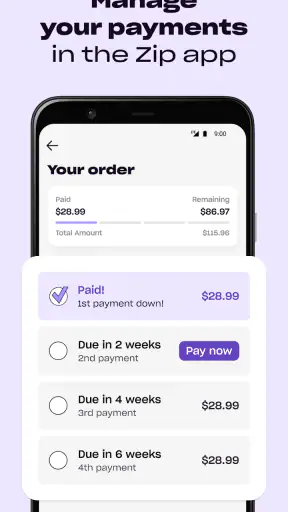
Once I open Zip, I treat the payment screen as a confirmation stage, not a prompt to spend more. I review the amount, the timing, and any terms presented before approving anything. This is one of the most useful workflows I can recommend because it separates shopping enthusiasm from payment commitment. The app can make the final step convenient, but I still need to provide the financial discipline.
I also keep a simple record of active purchases. It can be a note, a calendar reminder, or whatever method I already use for bills. The important point is to record the total obligation and the upcoming dates, not just the amount paid today. This is a practical safeguard that a store description will not tell you, and it becomes increasingly valuable when Zip is used at more than one merchant.
Another useful habit is to compare Zip with the merchant’s normal payment choices before selecting it. A debit card may be better when I can comfortably pay in full and want the cleanest possible transaction. A credit card may be preferable for someone who already has a disciplined repayment routine and values its particular protections or rewards. Zip earns its place when the payment schedule solves a real timing problem, not simply because the first installment looks smaller.
A realistic everyday scenario
Imagine that my washing machine stops working shortly before payday. I have checked the replacement options, chosen a model within a sensible budget, and confirmed that the merchant accepts Zip. Paying the whole amount immediately would leave my account uncomfortably low, while waiting could mean going without a necessary appliance. In that situation, flexible payments may give me a practical middle ground.
I would still check the final total, delivery details, return conditions, and payment schedule before placing the order. I would then note each future payment alongside my other bills. The app is valuable here because the purchase is necessary and the repayment plan solves a short-term cash-flow issue. It would be a weaker choice if I were using the same method to add an optional entertainment purchase simply because the full amount felt uncomfortable.
This scenario also shows why the app should not be judged only by how quick checkout feels. The real test comes later, when the scheduled payments arrive. A smooth purchase is not automatically a successful financial decision. Zip helps most when it supports a decision I have already made carefully.
Where Zip feels stronger than usual alternatives
Compared with paying directly from a bank account, Zip offers more timing flexibility. That can be useful when the purchase is urgent but my cash position is temporarily uneven. Compared with a retailer-specific plan, its ability to work across merchants is more convenient because I do not have to learn a completely different system for every store.
Compared with a traditional credit card, the appeal is a more purchase-focused experience. I can think about the individual order and its payment arrangement rather than placing everything into one revolving balance. That said, a credit card may be a better fit for someone who pays the statement in full, wants one consolidated account, or prefers the protections and rewards associated with that card.
Compared with simply waiting and saving, Zip is faster but less forgiving. Saving avoids a future payment commitment, while Zip lets me obtain the item sooner. I would choose the saving route for nonessential purchases and reserve Zip for situations where timing matters or where the payment schedule genuinely improves my budget management.
These comparisons lead to a clear conclusion: Zip is not universally better than a debit card, credit card, retailer plan, or saving first. Its advantage is narrower and more practical. It gives me another way to structure a purchase when the product makes sense and the timing of payment is the main obstacle.
The tradeoffs I would consider before using it
The first tradeoff is mental overhead. Each flexible purchase creates another obligation to remember. One plan may be easy to follow, but several overlapping plans can make a monthly budget harder to read. I would avoid opening a new payment arrangement without first checking what is already scheduled.
The second is the temptation effect. A lower immediate payment can make a product appear easier to justify than it really is. I find it helpful to ask, “Would I still buy this if I had to pay the full amount today?” If the answer is no, I pause. That question does not eliminate every good use case, but it prevents the payment method from making the shopping decision for me.
The third tradeoff is that the experience can vary with the merchant and transaction. The app’s broad Visa acceptance is convenient, but I still verify that the payment option is available for the purchase I am making and that the terms shown match my expectations. I would not assume that every store, basket, return, or order adjustment will behave exactly the same way.
Returns deserve particular attention. If I change my mind about an item, I follow the merchant’s return process and then check how the purchase appears in Zip afterward. I keep confirmation emails and receipts until the order is fully resolved. This is not a criticism unique to Zip; it is simply the sensible way to handle any purchase that combines a retailer order with a separate payment arrangement.
I also make privacy and account security part of the decision. A shopping payment app handles information connected with purchases and repayment, so I use a strong account password and avoid signing in on shared devices. I review the screens carefully before approving a transaction, especially when I have moved between a retailer and the payment app. Convenience should not mean rushing through account or payment prompts.
Who gets the most value from it
Zip is a strong match for shoppers who already budget carefully but occasionally need more timing flexibility. It can suit someone replacing an essential item, managing a planned household purchase, or buying from different merchants while wanting a consistent payment option. The best users are not necessarily people with the largest shopping budgets; they are people who understand their future cash flow and can keep track of several due dates if needed.
It may also help someone who dislikes tying a payment plan to one retailer. The ability to shop where Visa is accepted gives the app a wider role than a single-store financing button. I appreciate that flexibility because it lets me compare merchants on product, delivery, and returns instead of choosing a store merely because its payment plan is available.
I would be more cautious if my income is unpredictable, my budget is already stretched, or I have trouble tracking recurring commitments. In those situations, paying in full when possible or waiting until the money is available may be safer. Zip cannot remove the risk created by taking on more obligations than the budget can support.
I would also skip it for impulse shopping. If the main reason to use the app is that the full price feels too high, that is a warning sign rather than a benefit. The service is most sensible when flexibility supports a well-considered purchase, not when it disguises an unaffordable one.
What the app’s reputation tells me—and what it does not
The app has a 4.7 average and tens of thousands of written reviews, which tells me that many users find the core experience worthwhile. It has also passed the five-million-install mark, so it is not an obscure experiment with a tiny audience. Zip, Co. has kept the app active through version 1.252.1, and the Android requirement is version 8.1 or later.
Those details are useful when deciding whether the app is established enough for my needs, but they do not replace reading the terms attached to my own transaction. A high rating cannot tell me whether a particular payment schedule fits my income, and a large install base cannot guarantee that every merchant interaction will be frictionless. I use the reputation as reassurance about adoption, not as a reason to skip personal budgeting.
The Everyone age rating also makes the app approachable from a content perspective, but age suitability is not the same as financial suitability. A shopper still needs to understand the commitment being made and, where relevant, meet the account and transaction requirements presented during use. I would explain the payment schedule clearly to anyone in my household who is helping make the purchase rather than assuming the small installments speak for themselves.
My recommendation after using it as a payment tool
What I like most about Zip is the focused value of its central capability. It can turn a badly timed but sensible purchase into a manageable series of payments, and its usefulness is not restricted to one retailer. That combination makes it more practical than a store-only plan for shoppers who compare prices across different merchants.
What keeps me from recommending it without qualification is the need for active tracking. The app makes checkout easier, but it does not make future payments disappear. I would use it for a necessary purchase after checking the complete cost and schedule, then record the commitment immediately. I would not use it to rationalize an impulse buy or to cover a budget that is already failing.
My bottom line is simple: Zip is best when payment timing is the problem, not when the purchase itself is unaffordable. If that distinction fits your situation, this free shopping app from Zip, Co. is worth considering. If you prefer one monthly card statement, want to avoid future commitments, or can comfortably pay in full, your usual payment method may be the cleaner choice.
For me, that honest boundary is what makes the app useful. Zip does not need to replace every way of paying. It only needs to provide a clear, manageable alternative at the moment a worthwhile purchase and an inconvenient payday meet. Used with that purpose—and with the later payments treated as seriously as the first—it can be a helpful addition to everyday shopping.
Zip FAQ
What is Zip, and how does the app work?
Zip is a buy now, pay later app that allows eligible users to split the cost of purchases into several scheduled payments instead of paying the full amount immediately. After creating an account and receiving approval, you can use Zip at participating online or in-store retailers. The app displays your repayment schedule, available spending limit, and upcoming installments, helping you manage purchases from one place.
Is Zip available to everyone, and what are the eligibility requirements?
Zip is not automatically available to every applicant. Eligibility generally depends on factors such as your age, country or region, identity verification, payment method, account history, and the information provided during registration. Approval can vary for each purchase, even if you have used the service before. Before downloading, check whether Zip operates in your location and review its current user requirements.
Does Zip charge interest, fees, or other costs?
The cost of using Zip depends on the repayment plan, merchant, location, and the terms shown before you confirm a purchase. Some plans may advertise no traditional interest, but account, installment, late, or convenience fees can apply in certain situations. Always read the payment summary carefully, including the total repayment amount, due dates, and consequences of missed payments before accepting an order.
Can I use Zip for online and in-store purchases?
Zip can be used with supported merchants online and, where available, in physical stores. The exact process may differ: some retailers offer Zip directly at checkout, while others may require a virtual card or instructions provided inside the app. Availability also depends on your location, account status, and purchase amount. Confirm that the retailer and transaction are supported before relying on Zip to complete payment.
What happens if I miss a Zip payment or need a refund?
If a scheduled Zip payment is missed, the app may attempt to collect the amount again and may apply applicable fees or restrict future purchasing privileges, depending on the terms in your region. For refunds, you normally need to contact the retailer first, because Zip adjusts the repayment schedule after the merchant processes the refund. Continue checking your account until the refund and remaining installments are correctly updated.